Watch the video with chapters & transcript →
AI IN FINANCE
Is Anthropic's $2 Trillion IPO Valuation Justified?
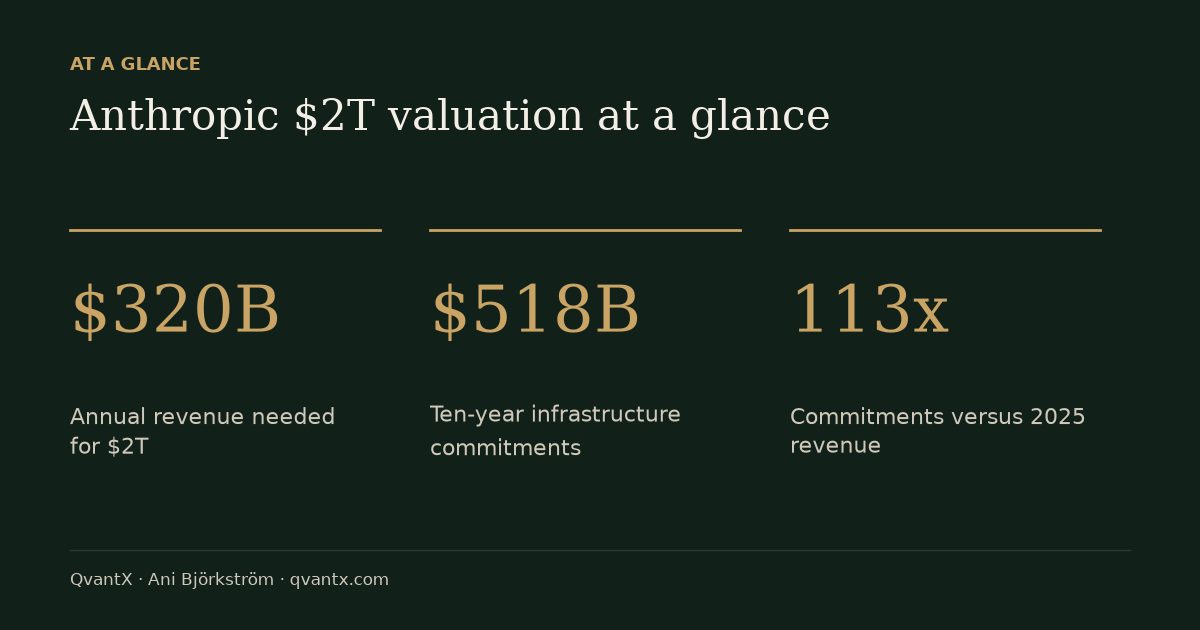
In short: Anthropic's $2 trillion IPO valuation is justified only if annual revenue reaches roughly $320 billion, about 7 times its current run rate of around $46 billion, according to its leaked draft S-1. Revenue is growing fast, but Anthropic has committed $518 billion to cloud, chips and data centers, about 80% non-cancelable. The filing is not final.
Key takeaways
- Anthropic needs roughly $320 billion in annual revenue to justify a $2 trillion valuation — about 7 times its current ~$46 billion annualized run rate.
- Of the headline $42 billion net loss on $4.6 billion of 2025 revenue, about $34 billion is non-cash accounting tied to convertible instruments; the real operating loss is closer to $8 billion.
- Anthropic has committed $518 billion to cloud, chips and data centers over the next decade, about 80% non-cancelable and 113 times 2025 revenue.
Ani Björkström, the Stockholm-based tech and finance consultant behind the YouTube channel AI for Finance, reads Anthropic's leaked draft S-1 the way a finance analyst would — line by line, past the headline loss and into the commitments, concentration risk and voting structure that actually determine whether a $2 trillion price tag holds up. The filing, reported by Reuters, is not final and the numbers can still change before the IPO, which Anthropic has reportedly pushed from October to November 2026. The company's last private round, in May, valued it at $965 billion; public investors are now being asked to pay roughly double that.
Why did Anthropic lose $42 billion in 2025?
Most of the $42 billion net loss is an accounting artifact, not cash leaving the company. About $34 billion of it stems from convertible instruments Anthropic used to raise money — as the company's valuation rose, the future shares those instruments convert into became more expensive, and accounting rules required booking that increase as a loss.
Strip that out and the real operating loss was about $8 billion, still roughly 1.8 times revenue. Compute was the dominant cost at $7.33 billion, or 58% of all spending. The scary $42 billion headline, in other words, is mostly paper.
How fast is Anthropic's revenue actually growing?
Anthropic's revenue jumped from $4.6 billion for all of 2025 to $4.7 billion in just the first quarter of 2026, then to $11.5 billion in the second quarter — a 2.4x increase in three months. Annualized, that second-quarter figure puts Anthropic on a roughly $46 billion revenue run rate.
The company was also operating-profitable for two consecutive quarters, undercutting the narrative that Anthropic is simply burning cash. This growth is the core of the bull case, but it has to be weighed against a far larger number: the spending Anthropic has already locked in.
What is the $518 billion risk behind the Anthropic IPO?
Anthropic has committed to spend $518 billion on cloud infrastructure, chips and data centers over the next decade, and about 80% of that is non-cancelable. That figure is 113 times Anthropic's entire 2025 revenue — comparable to signing a mortgage worth 113 times your current salary that you cannot walk away from.
Two further risks compound that bet. First, just two unnamed customers accounted for 25% of 2025 revenue, and many large clients lack long-term contracts, so losing either customer could erase a quarter of revenue overnight while the $518 billion bill stays fixed. Second, control: the seven co-founders hold Class F shares giving them 50.1% of the voting rights, leaving public shareholders with little say over major decisions.
| Metric | Figure | What it means |
|---|---|---|
| Headline net loss (2025) | $42B on $4.6B revenue | ~$34B is non-cash accounting on convertible instruments, not cash burn |
| Real operating loss | ~$8B | About 1.8x revenue; compute was $7.33B, 58% of spending |
| Revenue growth | Q1 2026 $4.7B → Q2 2026 $11.5B | 2.4x in one quarter; annualizes to a ~$46B run rate |
| Spending commitment | $518B over 10 years | ~80% non-cancelable; 113x 2025 revenue |
| Revenue needed for $2T valuation | ~$320B/year | About 7x the current ~$46B run rate |
FAQ
What valuation is Anthropic seeking in its IPO?
Anthropic is reportedly seeking around $2 trillion, roughly double the $965 billion valuation from its last private funding round in May.
Is Anthropic's $42 billion loss real cash burn?
No. About $34 billion of the $42 billion net loss is a non-cash accounting charge from convertible instruments revaluing as Anthropic's price rose; the underlying operating loss is closer to $8 billion.
Is Anthropic publicly traded?
Not yet. Anthropic is still a private company. Its last private funding round, in May 2026, valued it at $965 billion, and its IPO is reportedly planned for November 2026.
When is the Anthropic IPO date?
The Anthropic IPO has reportedly been pushed from October to November 2026, so investors can see third-quarter 2026 results before the shares are priced. The exact date is set only when the offering is priced.
Can you buy Anthropic stock on Avanza or Nordnet in Sweden?
Not before it lists. While Anthropic is private, no Swedish broker can sell its shares. Once it lists on a US exchange, the shares can be traded through brokers that offer US stocks, which Avanza and Nordnet both do. This is general information, not investment advice.
What is in Anthropic's leaked S-1 filing?
The draft S-1, reported by Reuters, shows a $42 billion net loss in 2025 on $4.6 billion of revenue (about $34 billion of it non-cash), $518 billion of spending commitments, two customers making up about 25% of revenue, and seven co-founders holding 50.1% of the vote through Class F shares. The filing is not final.
What single number will decide whether Anthropic is worth $2 trillion?
Third-quarter 2026 revenue. The video explains this is the reported reason the IPO was delayed from October to November — to let Anthropic show investors Q3 results before pricing the offering.
Read the full video transcript, with chapters, on the video page →
Want this working inside your finance team?
Ani Björkström — founder of QvantX Sweden AB, a Stockholm consultancy building AI solutions for banks, asset managers and finance teams. Anthropic partner. Every article starts from a real client build, minus the confidential parts. LinkedIn →
Keep reading — AI in Finance
 AI Stocks Just Lost $2.8 Trillion. Is the AI Bubble Popping?
 Why Are We Still Paying for Power BI? I Tested Claude Dashboards on a Real Excel Report
 AI's Circular Financing, Explained — Scam or Not?
 I Tested Claude for Excel: It Fixed My Broken P&L Model
More: all 64 articles · EU AI Act: What Actually Changes on 2 August 2026? · What is DBT and why so many companies use it? · What is Really like to be a CONSULTANT! · NVIDIA's True Value According to Claude AI (Spoiler: It's Wrong) · work with QvantX