Watch the video with chapters & transcript →
AI REGULATION
EU AI Act: what actually changes on 2 August 2026?
In short: The Digital Omnibus on AI (Regulation 2026/1744) moved the EU AI Act's full high-risk compliance deadline from 2 August 2026 to 2 December 2027, but Article 50 transparency rules still apply from 2 August 2026. Customer-facing AI must disclose itself in the conversation, and synthetic content needs machine-readable markings. Violations can be fined up to 15 million euros or 3% of turnover.
Key takeaways
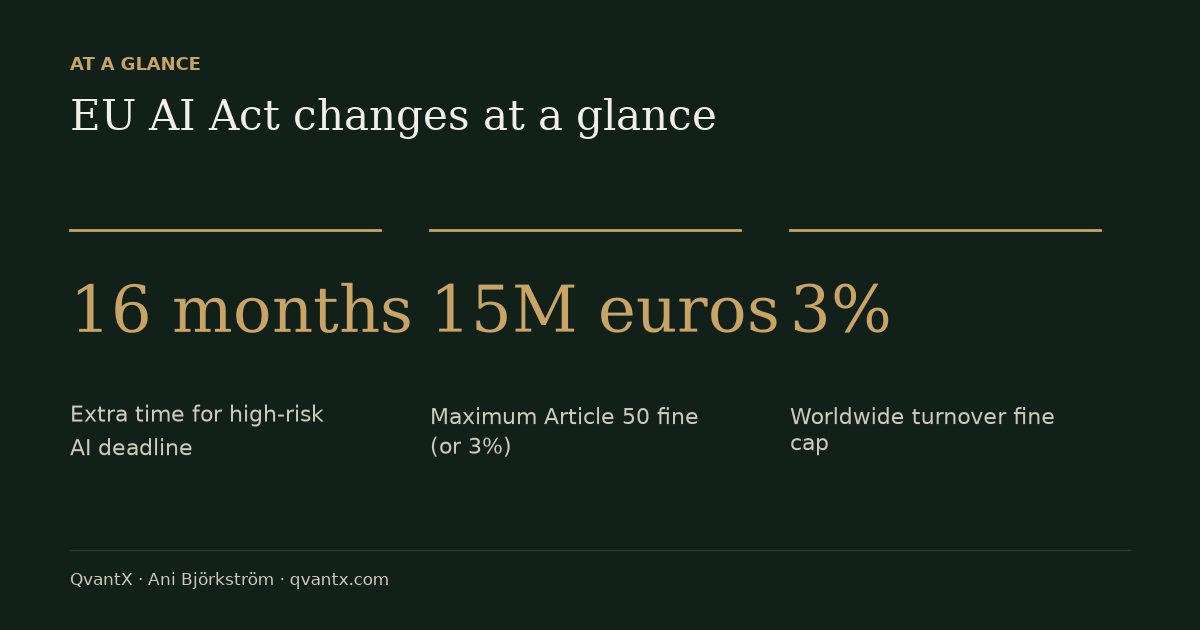
- The Digital Omnibus on AI (Regulation 2026/1744) moved the full high-risk compliance deadline from 2 August 2026 to 2 December 2027 — 16 extra months — entering into force six days before the deadline it was built to move.
- Article 50 transparency rules did not move: from 2 August 2026, customer-facing AI must disclose itself in the conversation, and synthetic content needs machine-readable AI markings.
- Violating Article 50 carries fines up to 15 million euros or 3% of worldwide annual turnover, enforced by national market surveillance authorities — not Brussels.
Almost everything published about the EU AI Act before this summer is out of date. The Parliament approved the Digital Omnibus on AI on 16 June (423 for, 57 against, 174 abstentions), and it hit the Official Journal on 24 July as Regulation 2026/1744.
Which EU AI Act deadlines moved?
High-risk AI under Annex 3 — credit scoring, insurance pricing, hiring, education — no longer faces its full compliance package on 2 August 2026; the deadline is now 2 December 2027. For AI embedded in regulated products like medical devices and industrial machinery, the date moved from August 2027 to 2 August 2028.
Delayed does not mean deleted. Existing model governance rules apply today, and the European Banking Authority has said rules like DORA already cover much of this ground — no compliance holiday.
What still applies from 2 August 2026?
Two things did not move: Article 50 transparency duties and enforcement over general-purpose AI providers. Article 50 contains four duties, and at least two almost certainly touch your business.
| Article 50 duty | Requirement from 2 August 2026 |
|---|---|
| Conversational AI | Chatbots, voice agents, and robo-advisors must disclose AI in the conversation itself — terms and conditions do not count. |
| Synthetic content | AI-generated text, images, audio, and video need machine-readable AI markings (metadata, watermarking). |
| Emotion recognition | People exposed to emotion recognition or biometric categorization — such as call sentiment analysis — must be informed. |
| Deepfakes and public text | Deepfakes need visible labels; AI-generated public-information text must be disclosed unless a named human editor takes responsibility. |
One nuance almost everyone gets wrong: systems on the market before 2 August get until 2 December 2026 to comply with marking, but anything launched after must be marked from day one. General-purpose AI provider obligations have applied since August 2025 — what is new is teeth: from 2 August the Commission's AI Office can demand documentation, run evaluations, and fine providers up to 15 million euros or 3% of global turnover. Fine-tuning or redistributing a model under your own name may make you a provider too.
What should banks and asset managers do before Monday morning?
Work through a five-point checklist: inventory every EU-facing conversational AI and add in-conversation disclosure; verify machine-readable marking survives your export pipeline; set a deepfake policy and name an editor for AI-drafted public content; check your vendors; and do not stand down your high-risk program — December 2027 arrives fast. An internal LLM copilot is not high risk by itself, but the moment it faces customers, the disclosure duty applies.
Financial institutions also keep their national financial supervisors — in Sweden, Finansinspektionen. Ani Björkström has condensed the analysis into a free one-page classification checklist, linked in the video description.
FAQ
Is credit scoring still high-risk AI?
Yes. Credit scoring for individuals remains high risk, as does AI pricing in life and health insurance — the obligations simply land on 2 December 2027 instead.
Who enforces the Article 50 fines?
National market surveillance authorities, not Brussels — up to 15 million euros or 3% of worldwide turnover, whichever is higher, under Article 99.
Are pre-2026 guides to the AI Act still usable?
Mostly not. Guides published before summer 2026 describe deadlines that have since moved, including explainers with hundreds of thousands of views.
Read the full video transcript, with chapters, on the video page →
Want this working inside your finance team?

Ani Björkström — founder of QvantX Sweden AB, a Stockholm consultancy building AI solutions for banks, asset managers and finance teams. Anthropic partner. Every article starts from a real client build, minus the confidential parts. LinkedIn →
Keep reading — AI Regulation
 Why OpenAI’s Hugging Face Hack is a Nightmare for Banking & Finance
 4 rules for your AI content (before you get fined)
 What Happens If the AI Bubble Bursts? Your Money, Explained Simply
 Why Did AI Stocks CRASH? Is the AI Bubble Popping? (The 4 Dominoes)
More: all 65 articles · US vs. China: AI FIGHT · Robot Maids in Every Home Soon? · Is the AI takeover coming? The alignment problem explained. · OpenAI Claims It Solved Navier-Stokes. 25 Fields Medalists Say Stop. · work with QvantX